

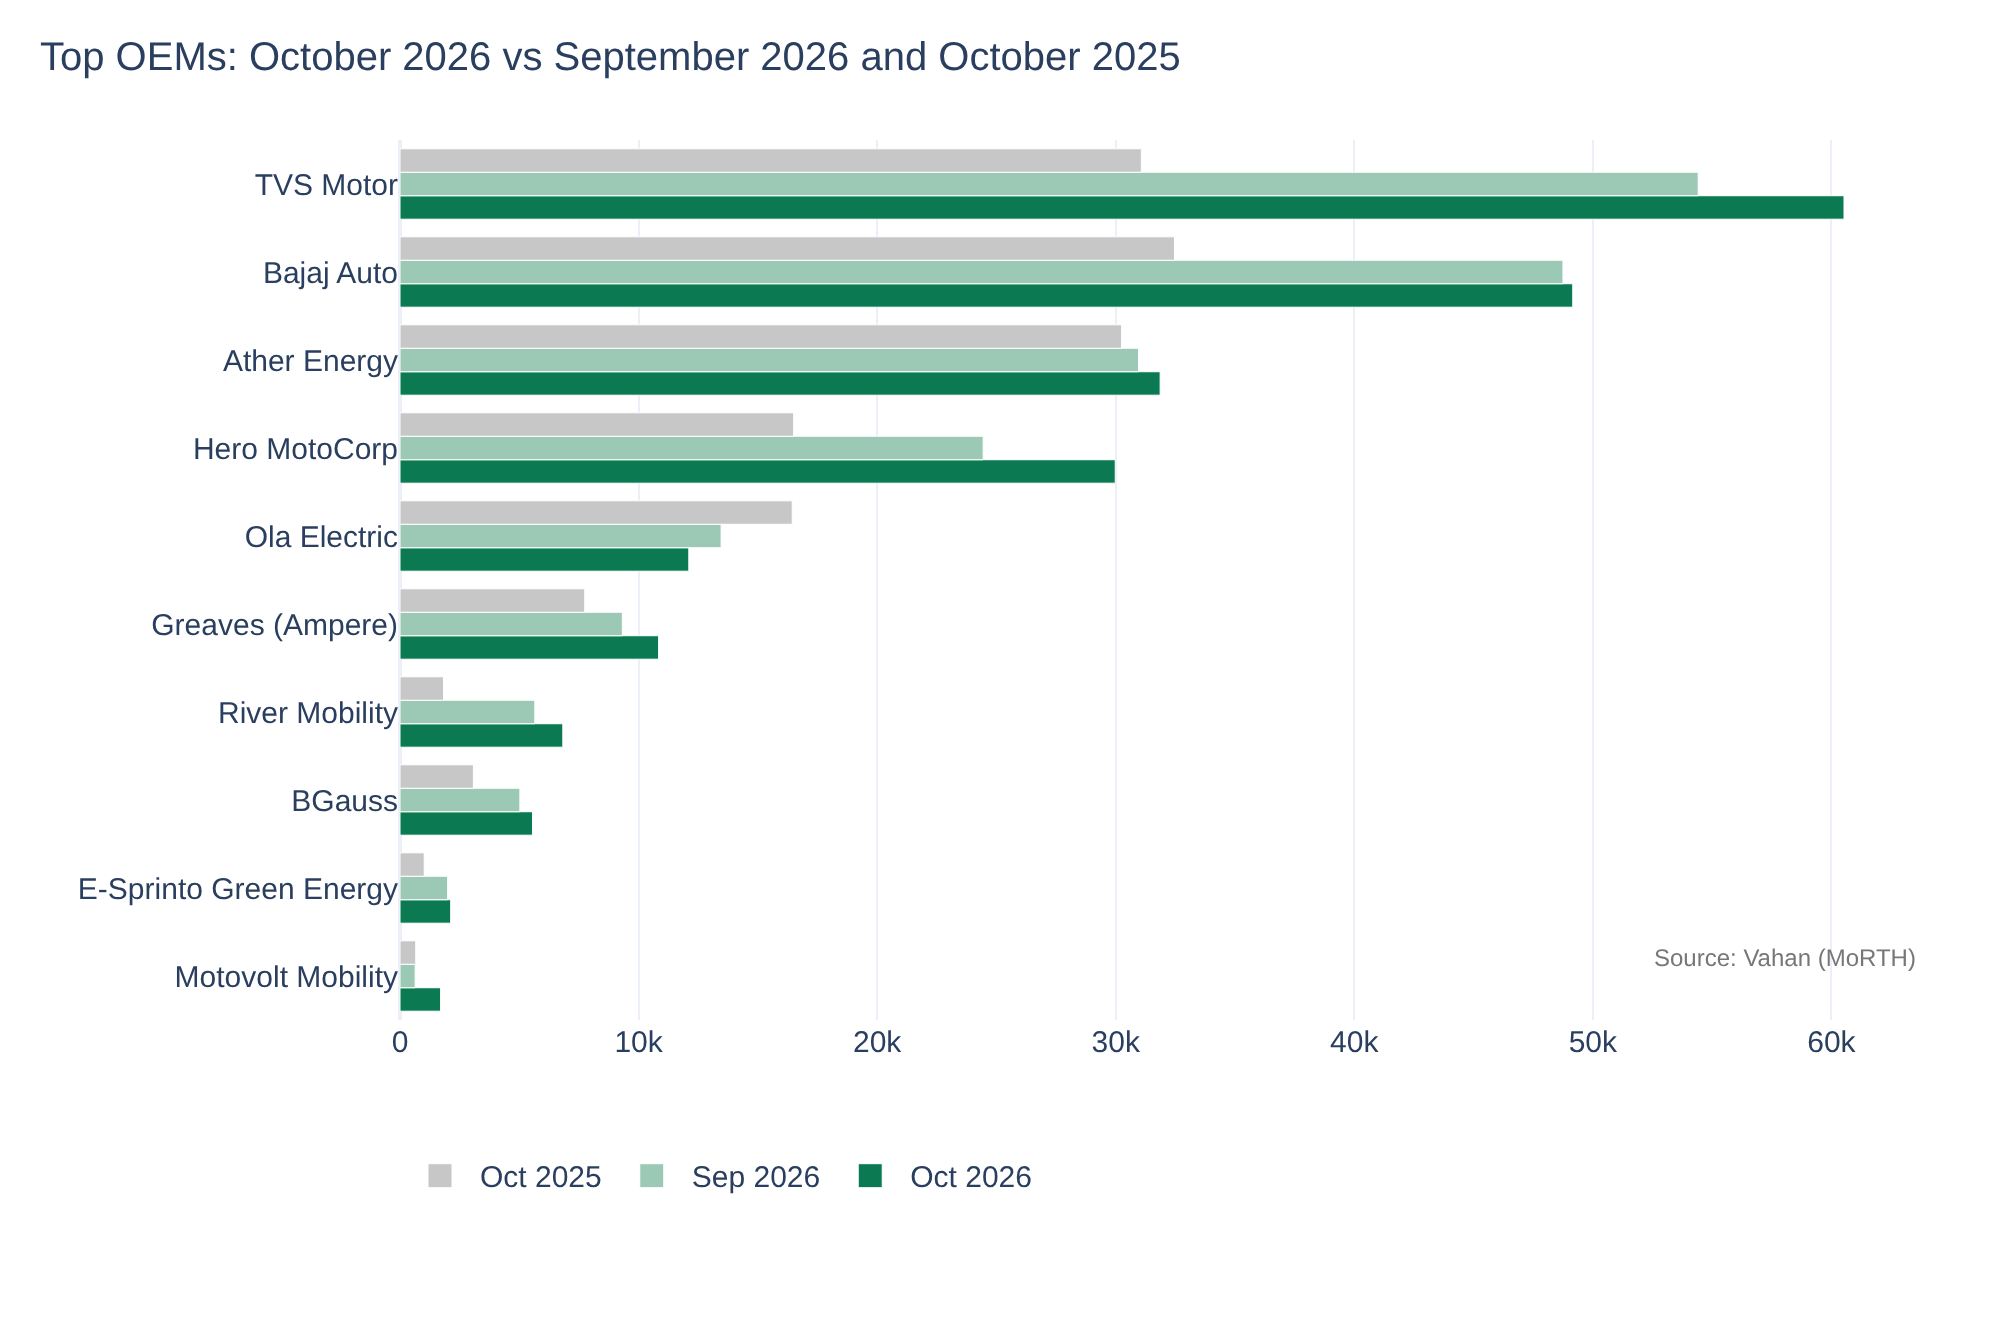
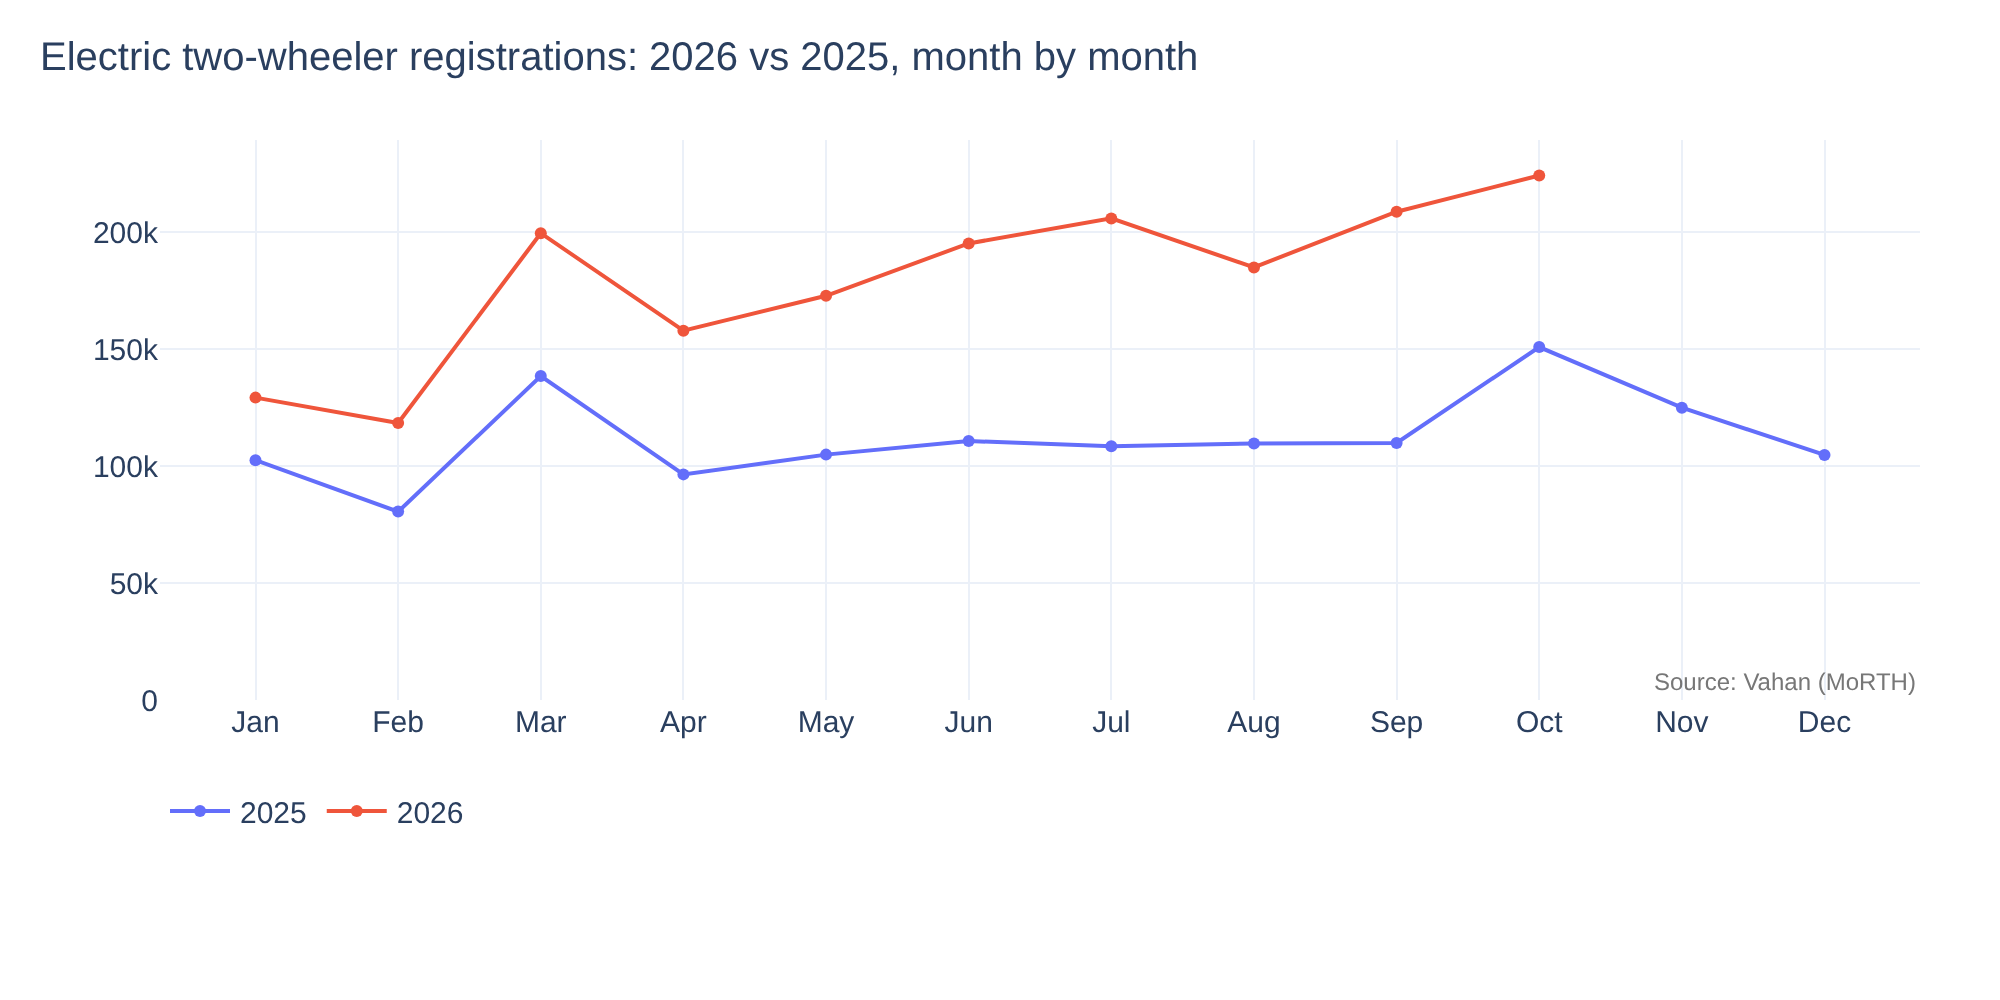
India registered 2,24,234 electric two-wheelers in October 2026, according to Vahan registration data. That is 7.4% more than in September (2,08,742) and 48.6% more than in October 2025 (1,50,895). It is the highest monthly total since at least January 2025, where this data set begins, and it follows September's record, which had already overtaken July's 2,05,893.
The gain came even as electric models lost ground in the wider market. All two-wheeler registrations rose 28.9% month on month, much faster than electric registrations, as the electric share of the market slipped to 9.7% from 11.6% in September. A year earlier that share stood at 4.7%: total two-wheeler registrations were 28.3% below October 2025, while electric registrations have risen by nearly half.
Who is leading the month
TVS Motor is leading for the twelfth month in a row, registering 60,527 units, up 11.2% from September. That is the company's highest monthly total in the data set; its previous best was 55,897. Its market share has risen to 27.0% from 26.1%.
Bajaj Auto is holding second place with 49,157 units, also its best month in the data set, but growth of only 0.8% is cutting its share to 21.9% from 23.4%. Ather Energy registered 31,862 units, up 2.9% on the month. Its year-on-year growth of 5.3% is far below the market's, so its share has fallen to 14.2%, from 14.8% in September and 20.0% a year earlier.
Hero MotoCorp posted the biggest gain among the leading OEMs: up 22.6% to 29,980 units, its highest in the data set, lifting its share to 13.4% from 11.7%. Hero is 1,882 units behind Ather for third place.
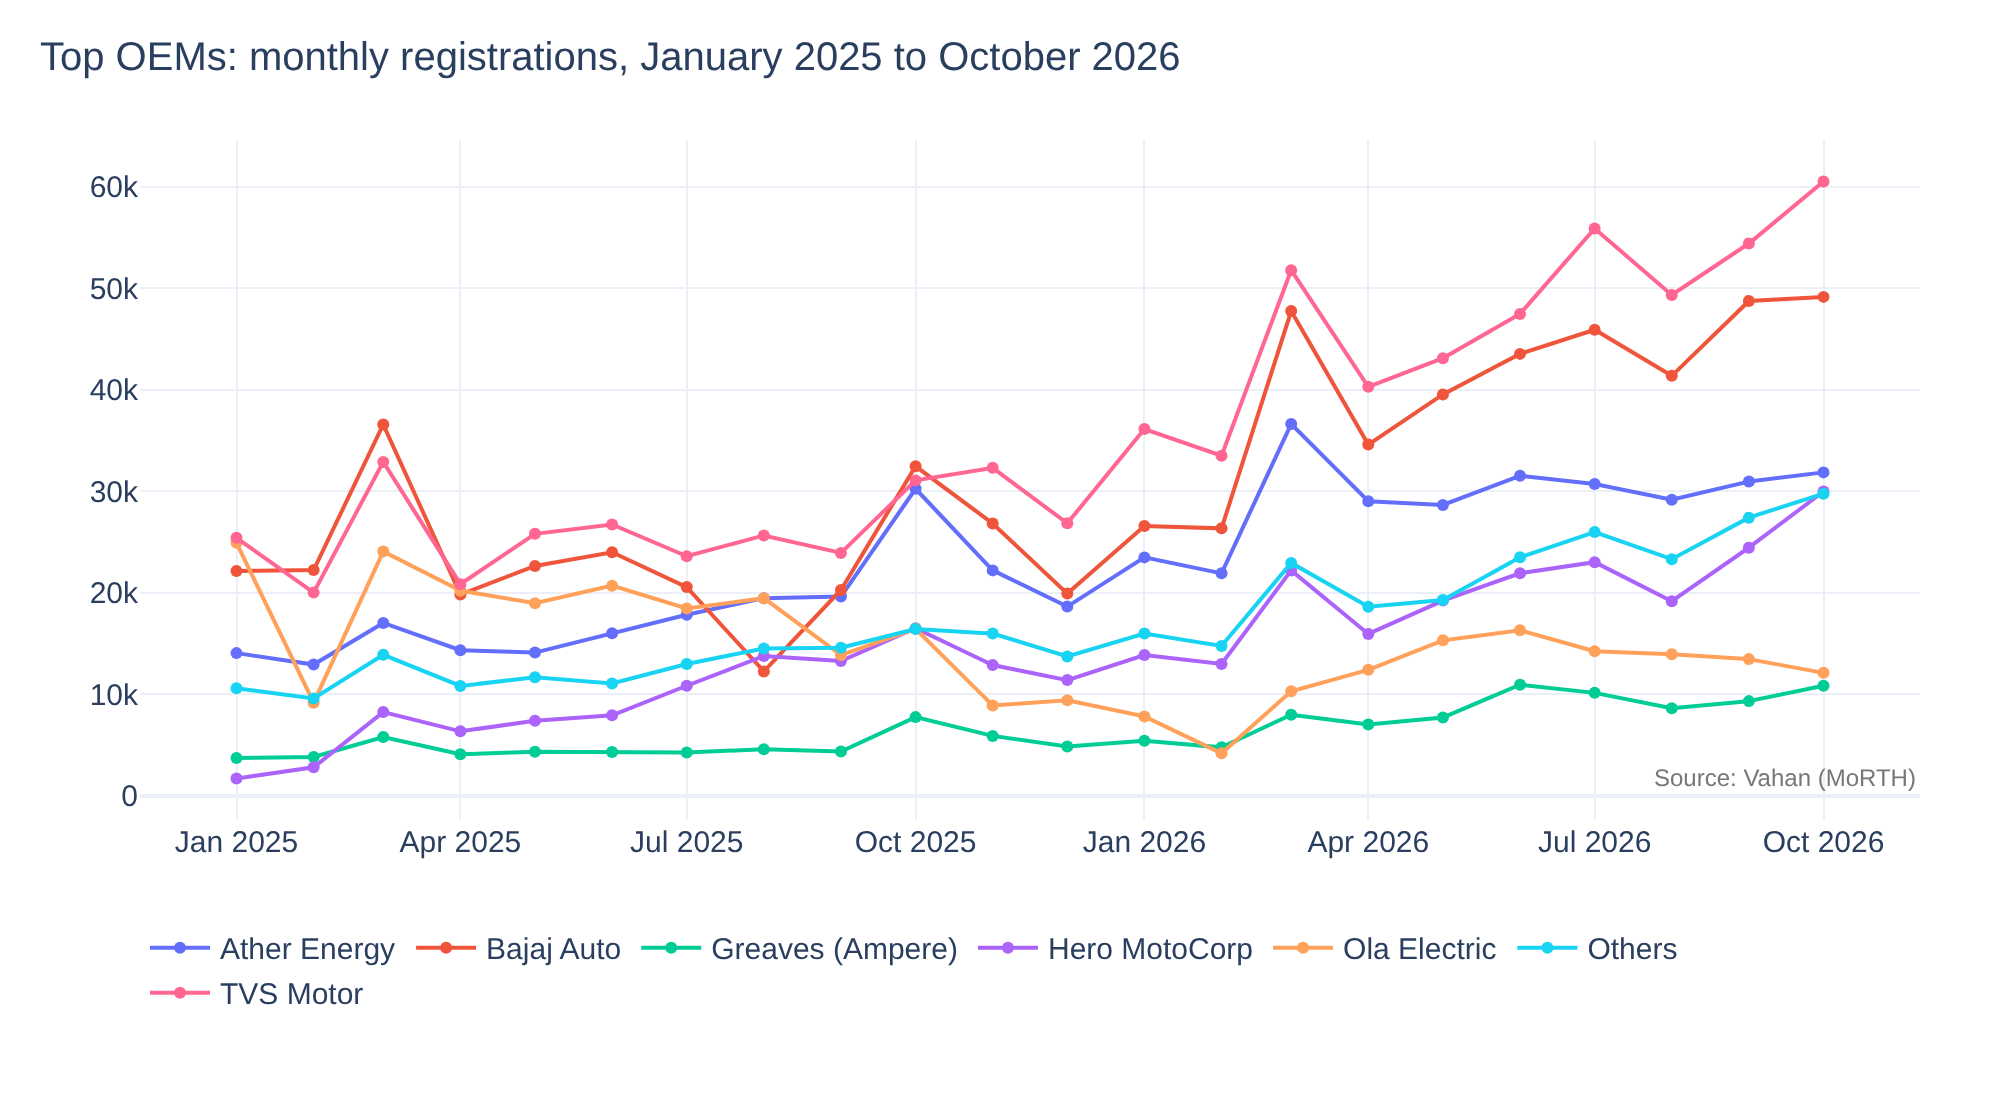
Ola Electric is going the other way. Registrations are down 10.1% to 12,105, 26.4% below a year earlier, and its share has dropped to 5.4% from 6.4% in September and 10.9% in October 2025.
Among smaller OEMs, Greaves Electric (Ampere) rose 16.3% to 10,839 units, while River Mobility gained 20.8% to 6,825, its best month in the data set and nearly four times its October 2025 volume. The four largest OEMs together are taking 76.5% of the market, up from 73.1% a year earlier.
| OEM | Oct 2026 units | MoM | YoY | Share | Sep share |
|---|---|---|---|---|---|
| TVS Motor | 60,527 | +11.2% | +94.8% | 27.0% | 26.1% |
| Bajaj Auto | 49,157 | +0.8% | +51.4% | 21.9% | 23.4% |
| Ather Energy | 31,862 | +2.9% | +5.3% | 14.2% | 14.8% |
| Hero MotoCorp | 29,980 | +22.6% | +81.7% | 13.4% | 11.7% |
| Ola Electric | 12,105 | −10.1% | −26.4% | 5.4% | 6.4% |
| Greaves (Ampere) | 10,839 | +16.3% | +40.0% | 4.8% | 4.5% |
| River Mobility | 6,825 | +20.8% | +274.4% | 3.0% | 2.7% |
| BGauss | 5,556 | +10.6% | +80.6% | 2.5% | 2.4% |
| E-Sprinto Green Energy | 2,124 | +6.4% | +109.3% | 0.9% | 1.0% |
| Motovolt Mobility | 1,702 | +168.0% | +158.3% | 0.8% | 0.3% |
| Others (101 OEMs) | 13,557 | 6.0% |
The trend is building
Between November 2025 and February 2026, monthly registrations stayed between 1,04,756 and 1,29,273. They jumped 68.5% to 1,99,578 in March, the last month of the financial year. After easing to 1,57,882 in April, they have risen in every month except August, and October is the peak so far.
Every month of 2026 is running above the same month of 2025. Year-on-year growth has slowed to 48.6% in October from 90.0% in September, but that mostly reflects a tougher comparison: October 2025 was itself up 37.3% on the month before.
Where the demand is coming from
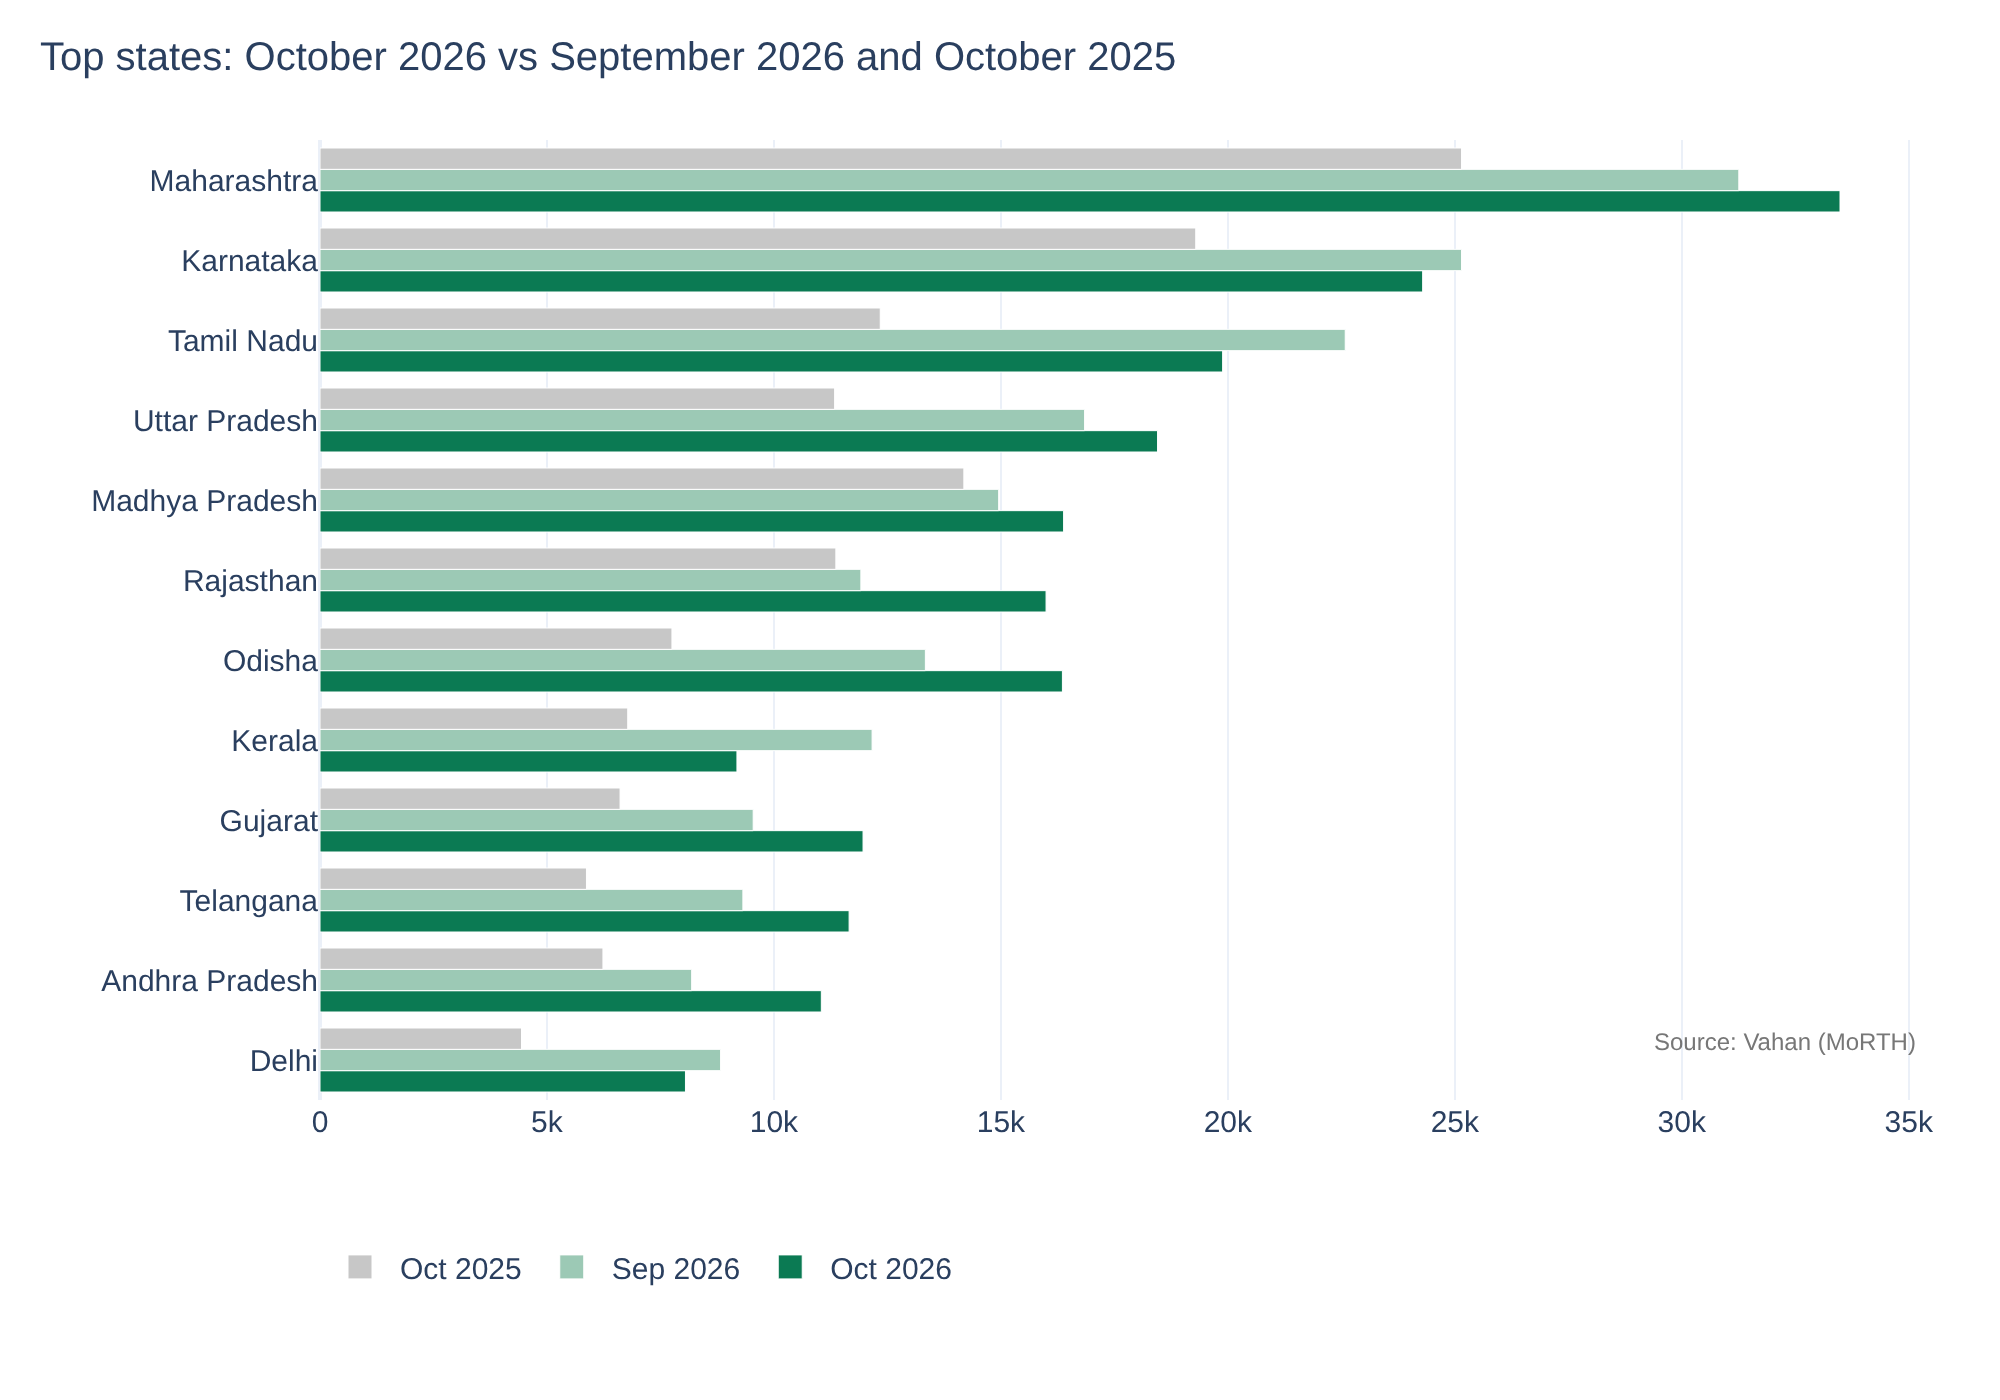
Maharashtra remains the largest market, with 33,485 registrations (14.9% of the national total), up 7.1% on the month. Karnataka (24,291) and Tamil Nadu (19,885) are following, but they are the only states in the top ten that are declining, down 3.4% and 12.0% respectively.
Among the top ten states, growth is strongest in Andhra Pradesh (+34.9%), Rajasthan (+34.2%), Gujarat (+25.4%), Telangana (+25.1%) and Odisha (+22.6%). Together, the ten largest states account for 80.1% of October's registrations.
| State | Oct 2026 units | MoM | Share |
|---|---|---|---|
| Maharashtra | 33,485 | +7.1% | 14.9% |
| Karnataka | 24,291 | −3.4% | 10.8% |
| Tamil Nadu | 19,885 | −12.0% | 8.9% |
| Uttar Pradesh | 18,451 | +9.5% | 8.2% |
| Madhya Pradesh | 16,381 | +9.6% | 7.3% |
| Odisha | 16,355 | +22.6% | 7.3% |
| Rajasthan | 15,995 | +34.2% | 7.1% |
| Gujarat | 11,963 | +25.4% | 5.3% |
| Telangana | 11,656 | +25.1% | 5.2% |
| Andhra Pradesh | 11,044 | +34.9% | 4.9% |
What to watch
Three things are worth tracking into November. First, whether Hero MotoCorp, now less than 2,000 units behind, keeps closing on Ather Energy for third place. Second, whether Ola Electric's decline is steadying after another fall in share. Third, whether the electric share of all two-wheeler registrations climbs back into the 10–12% range seen between June and September, after slipping below 10% in October.
Data: Vahan vehicle registration dashboard (Ministry of Road Transport & Highways), retrieved 5 November 2026. Registrations are the industry's usual stand-in for retail sales; they are counted by OEM and state of registration and may be revised as late entries are added. The electric share is electric two-wheeler registrations divided by all two-wheeler registrations in Vahan's vehicle-category data.
Related
- Delhi EV Policy 2.0: what the 2026–2030 rules mean for electric two-wheelers: subsidy rates, registration mandates and what the top five OEMs' base models cost in Delhi after subsidy.
- How to claim Delhi's electric two-wheeler subsidy: a step-by-step guide: eligibility checks, documents, the online application and deadlines.